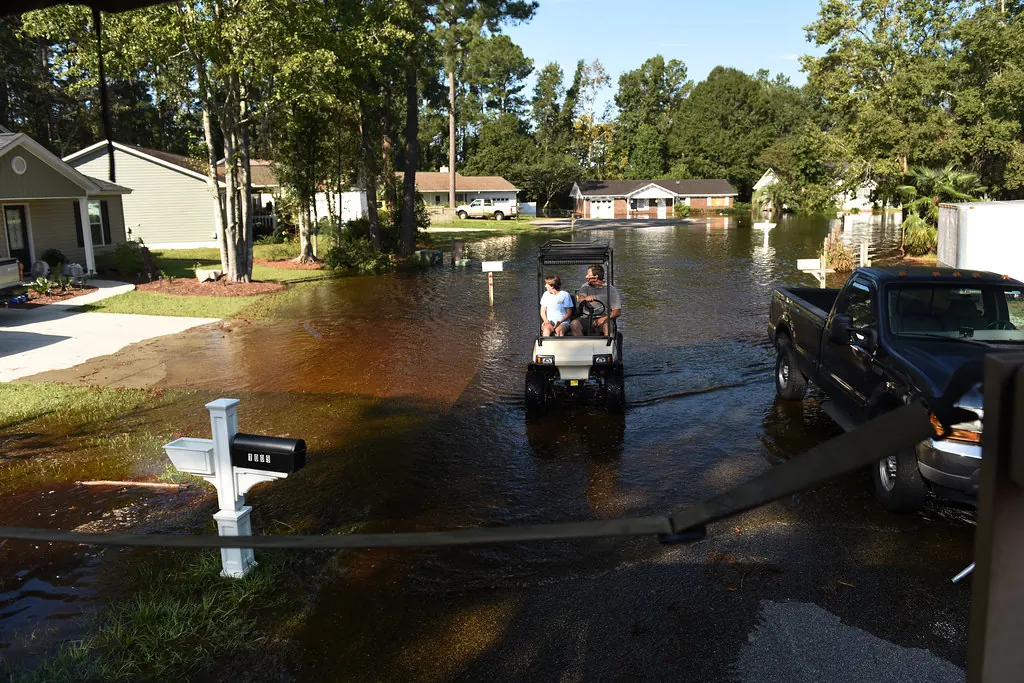
Why the split matters
Homeowners and commercial property policies generally cover windstorm and wind-driven rain through storm-created openings, while flood and storm surge are generally excluded and handled by a separate flood policy, such as one through the National Flood Insurance Program. When a single storm causes both, the allocation decides which policy pays and how much falls through the cracks.
How the worksheet calculates
- Items tagged wind go to the homeowners side; flood items go to the flood side.
- “Unclear” items are divided by the slider so you can see how sensitive the result is.
- The homeowners side subtracts the named-storm percentage deductible (or the flat one) and is capped at Coverage A.
- The flood side subtracts the flood deductible and is capped at the building limit you enter. Without a flood policy, flood damage stays with you.
Limits of a worksheet
Real allocations rest on evidence: water lines, debris, roof openings, weather data and sequence. Policies may also contain anti-concurrent causation wording that affects how mixed causes are treated, which is a coverage issue for the carrier, and possibly an attorney, rather than an appraisal panel. Every figure here is illustrative. Our guide to wind vs. flood claims explains documentation in more depth.
Questions about this tool
Can an appraisal panel decide what was wind and what was flood?
Appraisers can value damage, and some policies let them value it by cause. Whether a cause is covered remains a coverage question outside the panel.
Do flood policies cover contents?
Only if you bought contents coverage. Building and contents are separate limits on most flood policies.
Is any of this data stored?
No. The worksheet runs in your browser and nothing is sent or saved.