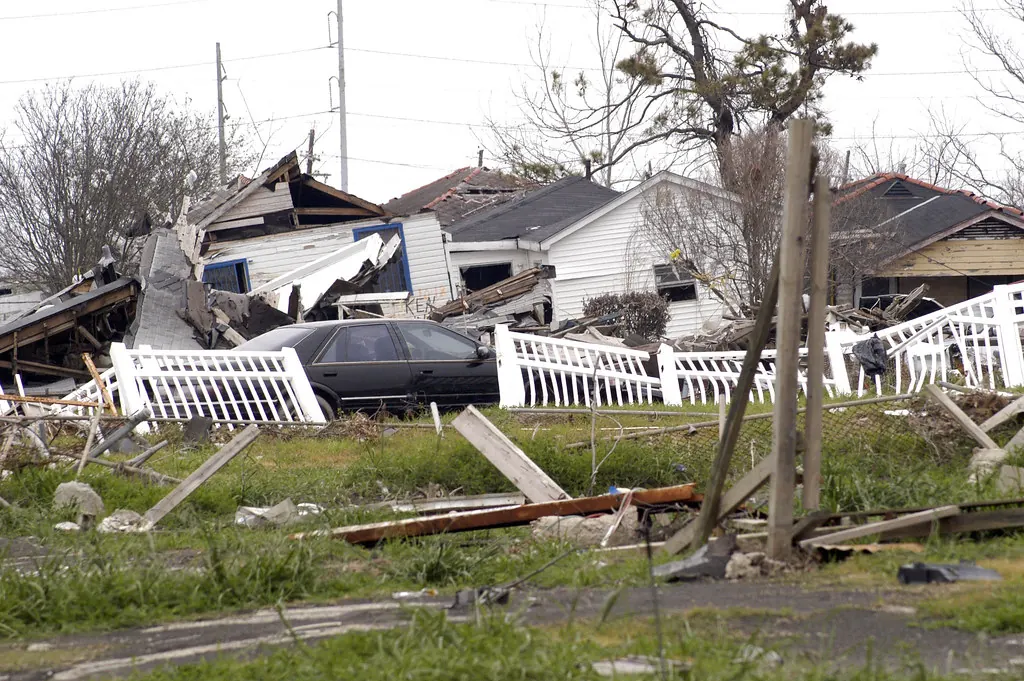
Wind damage isn’t always where you look first
North Carolina sees tornadoes in nearly every county over time, and the state has a long record of destructive outbreaks, from the March 1984 Carolinas outbreak to the April 16, 2011 storms that tore through Sanford and Raleigh. Most wind claims, though, come from ordinary severe thunderstorms: straight-line gusts that crease shingles, peel siding, topple fences and drop limbs.
The trouble is that wind damage is often subtle. Creased shingles may look flat from the ground but have lost their seal. A house that took a heavy gust may have racked framing, cracked drywall at window corners or doors that no longer close. Carriers sometimes estimate only what was obviously torn away.
What wind and tornado damage appraisal covers
- Shingle creasing, unsealing and uplift across every slope, not just the missing pieces.
- Siding, soffit, fascia and gutter damage, including matching on discontinued vinyl profiles.
- Interior consequences: ceiling cracks, nail pops, racked openings and water intrusion.
- Fences, sheds, carports, screened porches and other structures under Coverage B.
- Debris removal and, where the policy allows, tree removal and hauling.
Tornado-scale losses
When a home is heavily damaged or destroyed, the questions shift to whether the structure should be repaired or rebuilt, what code upgrades apply, and how the policy limits interact. Those claims need a complete replacement estimate, not a list of repairs.
Separate wind deductibles
Some North Carolina policies, especially near the coast, carry a separate wind/hail or named-storm deductible expressed as a percentage of dwelling coverage. Use our named-storm deductible calculator to see what that means in dollars before you compare settlement numbers.
Questions about wind & tornado loss appraisal
How do you prove shingle creasing was caused by this storm?
We document crease patterns, directionality, sealant condition and debris, and tie them to weather data for the date of loss. Fresh creases look different from long-term wear.
Is a tree falling on my house a wind claim?
Usually the damage the tree causes is covered under the peril that brought it down, often windstorm. Tree removal itself may have separate, smaller limits.
The carrier only paid for missing shingles. Is that normal?
It’s common, but it isn’t always right. If surrounding shingles are creased or unsealed, or replacements can’t be matched, the scope may need to be larger.