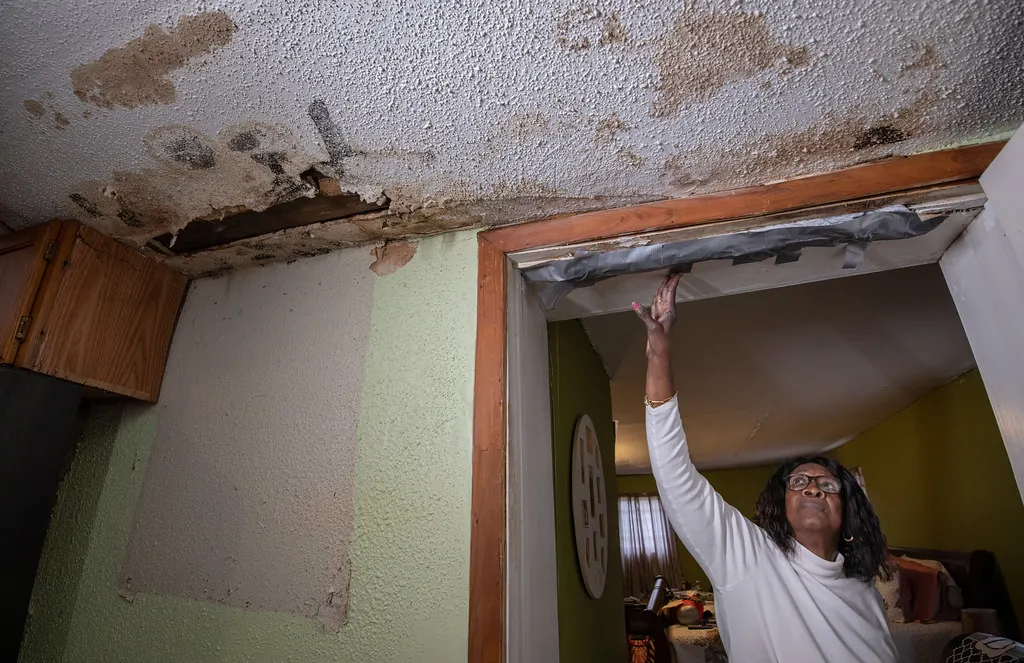
Why water claims come up short
Sudden and accidental water damage is covered by most homeowners policies, but water travels. It wicks up drywall, runs under cabinets, soaks subfloors and settles into crawlspace insulation. Estimates written after a quick walkthrough often stop at the visible stain.
- Partial-room repairs that leave a continuous floor or a painted wall impossible to match.
- Cabinets priced for a single damaged base unit when the run can’t be replaced in kind.
- Drying and demolition invoices cut back after the fact.
- Mold remediation capped by policy sublimits or disputed as “long-term.”
- Crawlspace damage to vapor barrier, insulation, ductwork and subfloor, especially common in Piedmont and Coastal Plain homes.
What water damage claim appraisal includes
We review the mitigation company’s moisture maps, photos and drying logs, then inspect the finished areas ourselves. Our estimate follows every affected material from the source to the end of the wet zone, and it treats flooring, paint and cabinets as the continuous systems they are in a real house.
Long-term leak and wear disputes
Carriers sometimes argue that a leak was gradual and therefore excluded. That is a coverage question, and appraisal won’t settle it. But when the carrier has accepted the loss and only the size of the repair is in question, appraisal is often the fastest way to close the gap.
Frozen pipes
Hard freezes reach the whole state every few winters, and the Christmas 2022 cold snap burst pipes from the mountains to the coast. Policies often require reasonable steps to maintain heat or drain the system, so keep utility records and thermostat details. Our ice storm and freeze damage page covers those claims in more depth.
Questions about water & plumbing loss appraisal
Will appraisal cover the mitigation company’s bill?
If the carrier accepted the loss and disputes the reasonable cost of drying and demolition, that cost can be part of the amount of loss presented to the panel.
The carrier will only pay to replace flooring in one room. Is that right?
Not necessarily. If the flooring runs continuously and can’t be matched, a larger area may be needed to restore the home to its pre-loss condition. Policy wording matters.
Is mold covered?
Many policies cover mold resulting from a covered water loss up to a sublimit. We value the remediation; the sublimit is set by your policy.