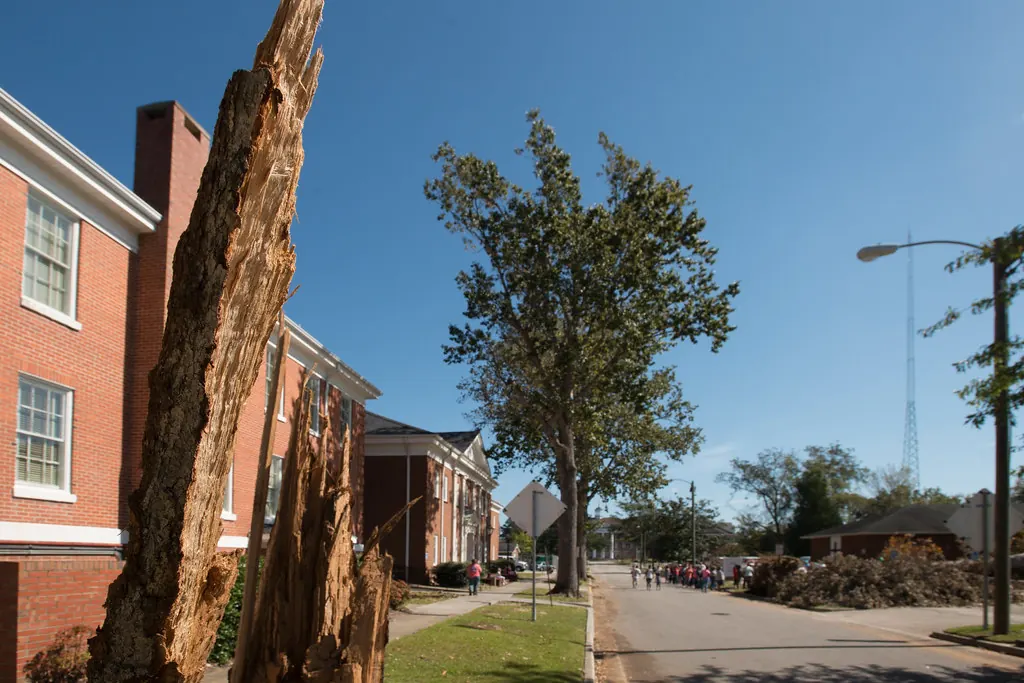
Fayetteville at a glance
- Hurricane winds
- River flooding
- Falling pines
- Tornado spin-ups
- Rental property damage
Housing: Fayetteville combines older homes in Haymount, large numbers of 1960s–1990s ranches and rental properties serving military families near Fort Bragg, manufactured homes in outlying areas, and newer subdivisions toward Hope Mills and the western part of the county.
Where we work: Haymount, Westover, Gillis Hill, Hope Mills, Spring Lake, Stoney Point, Vander, Eastover
Hurricanes that arrive inland
Fayetteville is roughly a two-hour drive from the coast, far enough that hurricanes usually lose some of their wind before they arrive but close enough that their rain does not. Matthew in 2016 and Florence in 2018 both brought extraordinary rainfall to the Sandhills. Water rose along the Cape Fear River, Cross Creek, Little River and smaller tributaries, and wind brought down tall pines onto roofs and vehicles throughout Cumberland County.
That combination makes cause the first question in many Fayetteville claims. Wind damage and wind-driven rain entering through a storm-created opening are typically handled under a homeowners policy. Rising surface water is generally excluded from standard homeowners coverage and handled by a separate flood policy, usually through the NFIP or a private insurer. When both happen to the same home, separating the damage is essential before anyone can agree on a number.
Housing patterns in Cumberland County
Haymount, one of the city’s oldest neighborhoods, has older homes with plaster, hardwood floors and established trees. Much of the rest of Fayetteville was built in the second half of the twentieth century, with brick and vinyl ranches and split-levels, many of them rental properties. Because of Fort Bragg, Fayetteville has a large share of homes owned by military families who rent them out after a reassignment, and owners are often managing a claim from another state or overseas.
Manufactured homes are common in outlying parts of the county and in nearby towns, and they have their own construction and pricing issues. Newer subdivisions toward Hope Mills and Gillis Hill raise familiar questions about matching roofing and siding.
Disputes we see after Sandhills storms
- Wind versus flood allocation on homes with both types of damage.
- Roof replacement versus repair after tall pines fall across a ridge.
- Loss-of-rent calculations for landlord policies.
- Manufactured home components priced like site-built construction.
- Mold and drying scope after prolonged water exposure.
- Contractor pricing after a regional storm compared with pre-storm estimates.
When owners are far away
A service member who has been reassigned, or a landlord who lives elsewhere, may not be able to walk the property with an adjuster. Appraisal can be useful in those situations because it puts the valuation in the hands of appraisers who inspect and document the loss. When a policy includes an appraisal clause and it is invoked, each side typically selects an appraiser, the two appraisers choose an umpire, and an agreement of two sets the amount. It is limited to the value of the loss and does not resolve coverage issues.
We act as party appraisers, as umpires and as estimate reviewers. An honest review sometimes shows the insurer’s estimate is close, and we will say so.
Where we work around Fayetteville
We serve Fayetteville from Haymount and Westover to Gillis Hill, as well as Hope Mills, Spring Lake, Stoney Point, Vander and Eastover, and nearby communities in Hoke and Harnett counties.
Storm history around Fayetteville
- 2016Hurricane MatthewMatthew’s rainfall pushed the Cape Fear River and local creeks into neighborhoods across Cumberland County, causing major flood damage.
- 2018Hurricane FlorenceFlorence stalled over the Carolinas and its rain flooded areas along the Cape Fear River and Little River, while winds downed trees across the county.
Services available in Fayetteville
Every North Carolina Insurance Appraiser service is available to property owners in Fayetteville and across Cumberland County:
- Appraisal Panel Representation
- Residential Claim Disputes
- Commercial, HOA & Condo Claims
- Roof & Hail Loss Appraisal
- Wind & Tornado Loss Appraisal
- Hurricane & Tropical Storm Claims
- Water & Plumbing Loss Appraisal
- Fire & Smoke Loss Appraisal
- Ice Storm & Freeze Damage
- Carrier Estimate Audit
- Neutral Umpire Services
Questions from Fayetteville property owners
I’m stationed away from Fayetteville and my rental was damaged. Can appraisal still work?
Yes. Appraisal does not require you to be at the property. Appraisers inspect the home, review estimates and document the loss, and you can authorize access through a property manager or tenant. If your landlord policy includes an appraisal clause and the claim is accepted, the amount can be resolved without you traveling back.
My Hope Mills home had wind and flood damage from the same storm. How is that handled?
Wind damage typically falls under your homeowners policy, while rising water is generally excluded and handled by a separate flood policy if you have one. The two claims are evaluated separately. Appraisal applies to amount-of-loss disputes under the policy covering the damage, so separating wind and water damage carefully is the first step.
Does appraisal work for a manufactured home in Cumberland County?
It can. Many manufactured home policies include an appraisal provision. These homes have specific components, such as roofing systems, wall panels and underbelly materials, that are priced differently from site-built homes. We review the policy and estimate to see whether those components were priced correctly before advising on appraisal.