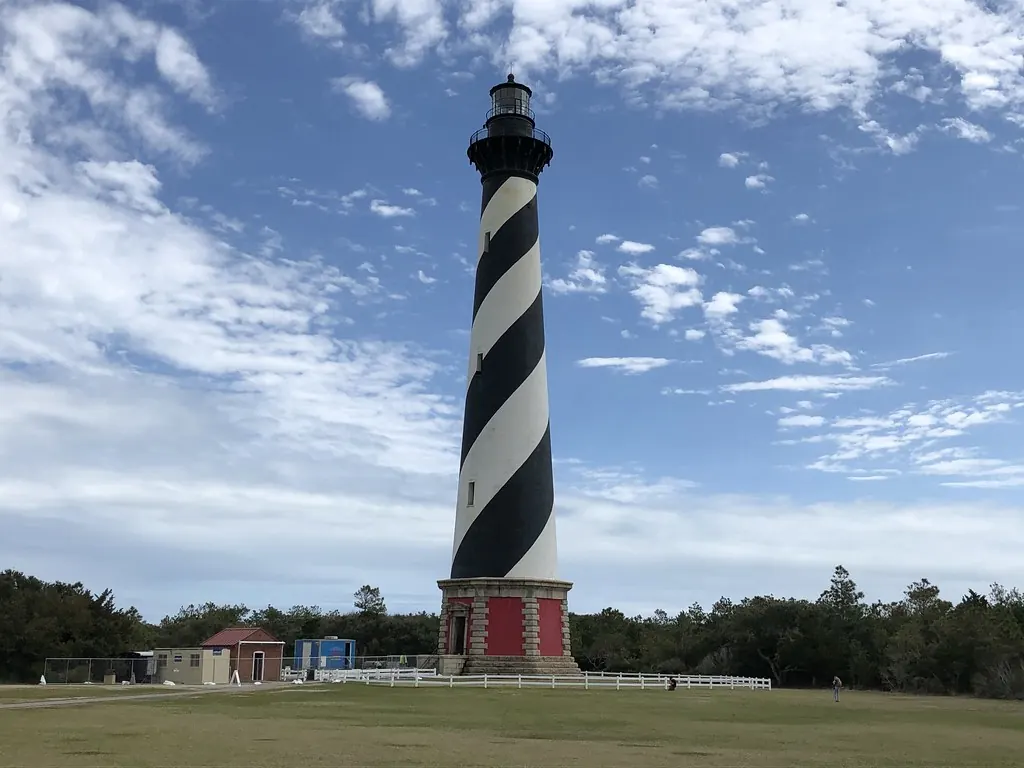
Outer Banks at a glance
- Hurricane winds
- Nor’easters
- Overwash and surge
- Salt corrosion
- Roof and siding loss
Housing: The Outer Banks are dominated by raised beach homes on pilings, many of them large vacation rentals, along with older flat-top and cottage-style homes in Nags Head and Kill Devil Hills, soundside homes, and historic buildings in Manteo.
Where we work: Duck, Southern Shores, Kitty Hawk, Kill Devil Hills, Nags Head, Manteo, Rodanthe, Avon, Hatteras
Barrier islands, constant weather
The Outer Banks stretch along a narrow chain of barrier islands, exposed to the Atlantic on one side and the sounds on the other. Hurricanes get most of the attention, but nor’easters also cause serious damage, sometimes lingering through several tide cycles. The Ash Wednesday Storm of 1962 remains a reference point, and Isabel in 2003, Irene in 2011 and Dorian in 2019 each showed how quickly the islands can be cut off.
Wind is the main source of homeowners claims: shingles, siding and trim torn away, decks and stairs damaged, windows and doors broken and wind-driven rain forced into walls. Overwash, surge and rising sound water are a different category. Standard homeowners and wind policies generally exclude flood, which is usually insured through the NFIP or private flood policies. Separating wind from water damage is often the first and most important task.
How beach properties are insured
Many Dare County owners buy wind and hail coverage through the North Carolina Insurance Underwriting Association, the Coastal Property Insurance Pool that serves beach and coastal areas of 18 counties. Some pair a homeowners or dwelling policy that excludes wind with a separate pool wind policy and a flood policy. Knowing which policy responds to which damage matters, because appraisal applies to amount-of-loss disputes under the policy that covers the damage.
Raised homes and rental properties
Most newer beach homes are built on pilings, with large decks, multiple stories, cedar shakes or fiber-cement siding and metal or architectural shingle roofs. Many are vacation rentals, and some have pools, elevators and hot tubs. Older flat-top and cottage-style homes in Nags Head and Kill Devil Hills carry different construction details. Salt air speeds corrosion of fasteners, flashing and metal components, which can lead to arguments over what is storm damage and what is long-term deterioration.
Where beach-house estimates diverge
- Wind versus overwash or flood allocation.
- Corrosion and wear claims used to reduce wind damage.
- Decks, stairs and walkways on raised homes priced too low.
- Material and labor costs on remote islands, including transport.
- Loss of rental income for vacation rental owners.
- Cedar shake and specialty siding priced as standard materials.
Appraisal on the Outer Banks
Repair costs on the islands often run higher than inland because materials and crews have to come over the bridges or by ferry, and demand spikes after a storm. If your insurer has accepted a claim and you disagree on the amount, an appraisal clause may allow either side to invoke appraisal. Typically each side selects an appraiser, the two appraisers choose an umpire and an award agreed by two of the three determines the amount of loss. Appraisal does not decide coverage.
We act as party appraisers, umpires and estimate reviewers. We are not attorneys or public adjusters.
Where we work
We serve the Outer Banks from Duck and Southern Shores through Kitty Hawk, Kill Devil Hills, Nags Head and Manteo, and down Hatteras Island to Rodanthe, Avon, Buxton and Hatteras, as well as Corolla and Ocracoke.
Storm history around Outer Banks
- 1962Ash Wednesday StormA powerful nor’easter battered the Outer Banks over several tide cycles, destroying homes and reshaping the beaches.
- 2003Hurricane IsabelIsabel cut a new inlet through Hatteras Island, isolating the village of Hatteras until the gap was filled.
- 2011Hurricane IreneIrene breached NC 12 on Hatteras Island in several places, cutting off villages on the island.
- 2019Hurricane DorianDorian’s soundside surge flooded much of Ocracoke Island, damaging homes and businesses.
Services available in Outer Banks
Every North Carolina Insurance Appraiser service is available to property owners in Outer Banks and across Dare County:
- Appraisal Panel Representation
- Residential Claim Disputes
- Commercial, HOA & Condo Claims
- Roof & Hail Loss Appraisal
- Wind & Tornado Loss Appraisal
- Hurricane & Tropical Storm Claims
- Water & Plumbing Loss Appraisal
- Fire & Smoke Loss Appraisal
- Ice Storm & Freeze Damage
- Carrier Estimate Audit
- Neutral Umpire Services
Questions from Outer Banks property owners
My Nags Head rental home has a pool wind policy. Can I use appraisal for a wind claim?
Policies issued through the North Carolina Insurance Underwriting Association generally contain an appraisal provision. If the insurer accepts your wind claim and you disagree on the amount, appraisal may be available. We review your specific policy form first, because its wording controls the process and timelines.
The adjuster says the damage to my Kill Devil Hills home is corrosion, not wind. What now?
Salt air causes corrosion over time, and insurers often argue that metal components failed from deterioration rather than wind. An appraiser examines the damage pattern, fasteners and storm data to distinguish wind damage from long-term wear when measuring the amount of loss. A broader coverage dispute is outside appraisal.
Repairs on Hatteras Island cost more than on the mainland. Is that considered?
Appraisal aims to determine the reasonable cost to repair the damage where the property is located. On Hatteras Island, transporting materials and crews, limited contractor availability and post-storm demand can increase costs. We document those local factors so the appraisal reflects realistic island pricing.